SEC Crypto Custody Rules: What Advisers Need to Know
In brief
Current as of 2026-10-02.
- The SEC has proposed a custody framework that would clarify how registered investment advisers and regulated funds may hold crypto assets, replacing what Chairman Paul Atkins called "the grey of uncertainty created by custody rules crafted for a bygone era."
- The proposal would permit limited self-custody by advisers when no qualified custodian is available, allow state-chartered trusts to serve as custodians, and update audit and broker-dealer custodial rules.
- The rules are not final: a 60-day public comment period opens once the proposal is published in the Federal Register, after which the SEC can revise the text before any adoption vote.
What changed
The U.S. Securities and Exchange Commission proposed a new rule on October 1, 2026 that would establish a regulatory framework for the custody of crypto assets by investment advisers and regulated funds. The proposal was issued under the Investment Advisers Act of 1940 and the Investment Company Act of 1940, and it addresses a long-standing bottleneck: advisers must keep client assets with "qualified custodians," but it has been unclear which crypto arrangements satisfy that standard, leaving many firms hesitant to offer digital-asset strategies.
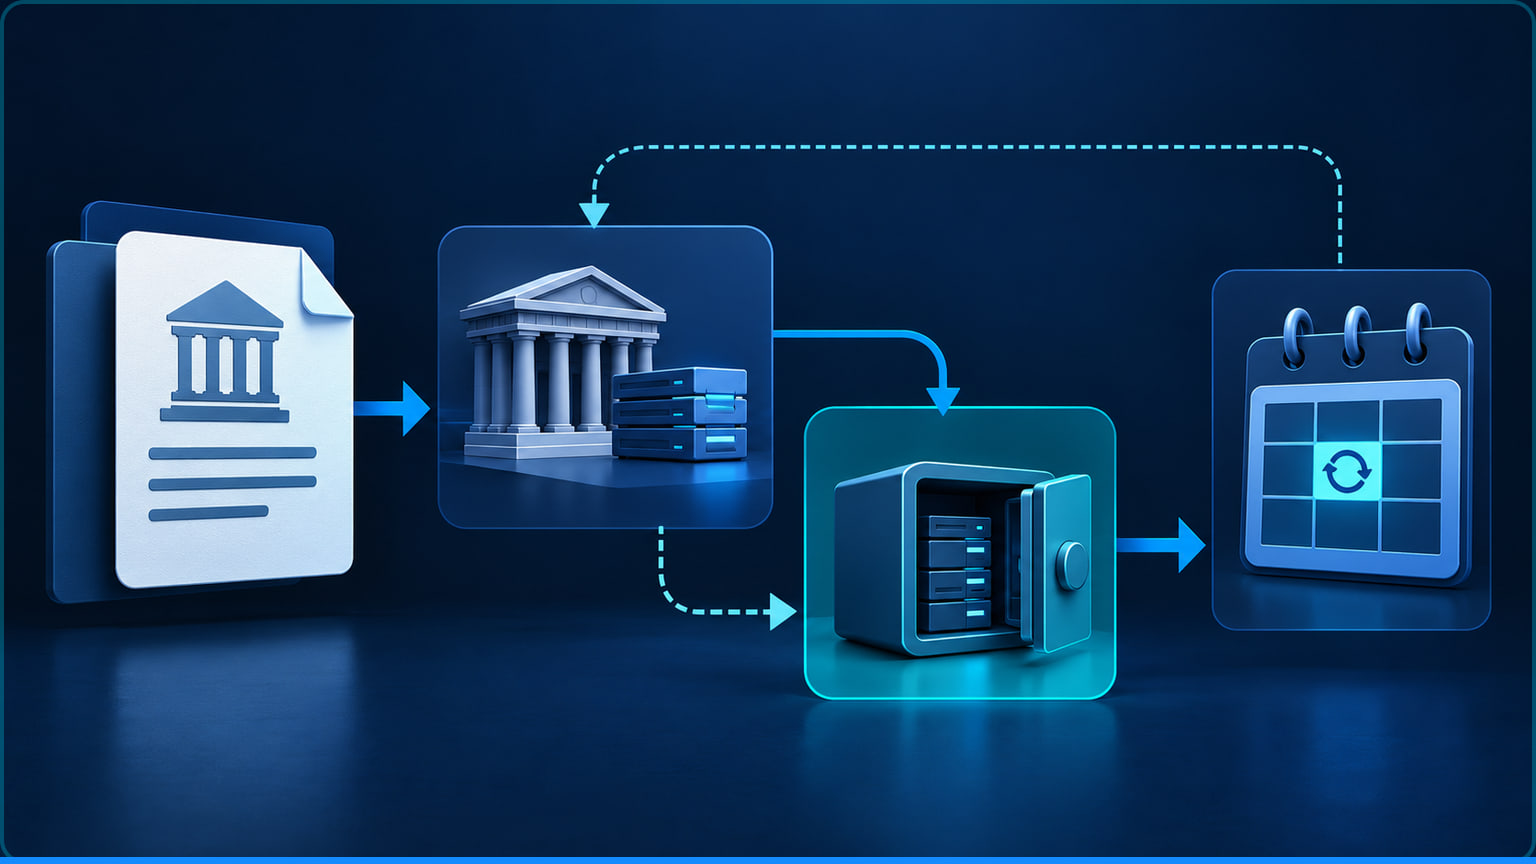
The proposal introduces several structural changes. It would allow self-custody by advisers seeking to hold their clients' funds, but only if the adviser cannot find a qualified custodian ready to take the assets and the adviser has certain required expertise. That self-custody ability would have to be reviewed every quarter to determine whether a custodian has become available. The proposal would also permit the use of state-chartered trusts as custodians for client and fund crypto assets, and it would update rules around financial-statement audits for advisers and broker-dealer custodial services for funds.
Section source: SEC maps out crypto custody in new proposal that furthers its digital assets agenda and SEC Proposes Rules to Clear Up How Advisers and Funds Can Hold Crypto
The custody proposal is the latest piece of the SEC's digital asset agenda, following the "Innovation Exemption" for tokenizing securities and the proposed Regulation Crypto Asset on fundraising using digital assets. The proposal was published the day before Commissioner Hester Peirce, who had led the SEC's Crypto Task Force since its inception, left the agency. The SEC also moved earlier in the week to reduce the number of commissioners required to form a quorum from three to two.
Section source: SEC maps out crypto custody in new proposal that furthers its digital assets agenda
Why it matters
For advisers and fund managers, the proposal signals a shift from regulatory ambiguity toward defined operating models for holding digital assets. The stated goal is to widen investor access to crypto strategies by removing barriers that have kept advisers on the sidelines. In practice, that may mean more firms can evaluate digital-asset products without first resolving an open-ended legal question about custody.
The self-custody provision is narrower than it may first appear. An SEC official said the circumstances for self-custody would likely be unusual after the rule is implemented, though it could apply to a newly launched token that custodians did not yet support. The quarterly review requirement means self-custody is not a stable end-state but a temporary fallback that must be re-justified every three months.
Section source: SEC maps out crypto custody in new proposal that furthers its digital assets agenda
For technology and compliance teams, the proposal introduces concrete operational questions. Teams will need to assess whether their custody arrangements meet the proposed qualified-custodian standard, whether state-chartered trust custodians are viable for their asset mix, and what audit evidence they would need to produce under the updated financial-statement rules. The proposal is not final, so these are planning questions rather than immediate obligations, but the direction is clear enough to justify preparatory work.
Section source: SEC Proposes Rules to Clear Up How Advisers and Funds Can Hold Crypto
IT Finance perspective: what this means in practice
The proposal matters less for what it mandates today than for the operating model it anticipates. Firms that have deferred digital-asset product decisions because custody was unresolved now have a concrete text to design against. That is a meaningful change, but it does not remove the need for careful architecture and vendor due diligence.
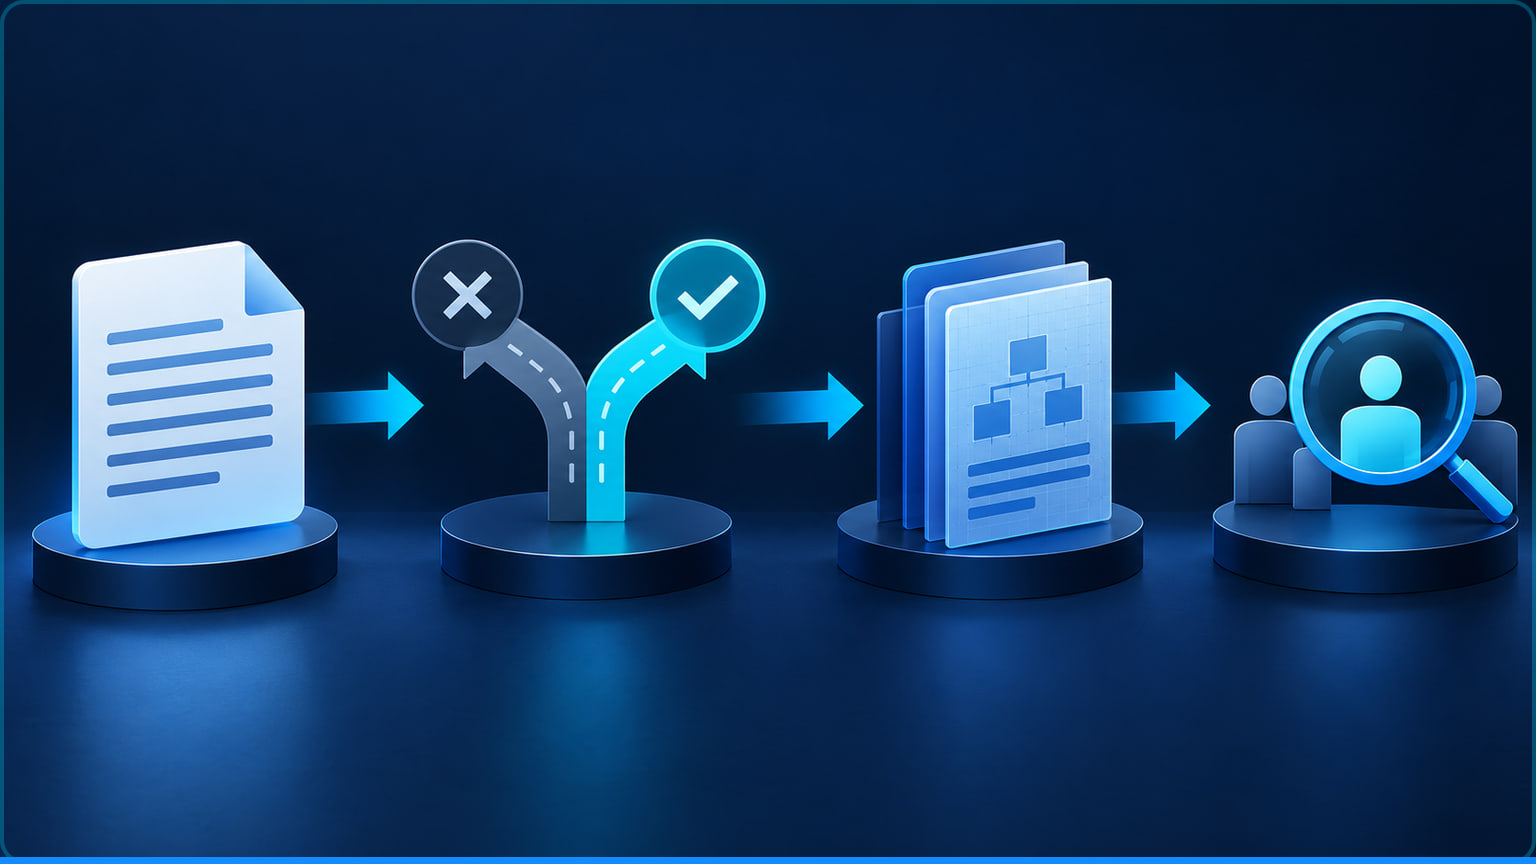
Three practical implications stand out. First, the qualified-custodian question becomes a vendor-selection exercise rather than a legal unknown. Teams can begin mapping which custodians — including state-chartered trusts — could support their target asset list, and which assets would fall outside that coverage. Second, the self-custody fallback creates a narrow but real operational path for newly launched or thinly supported assets. Any firm considering that path should treat the quarterly review requirement as a compliance trigger, not a formality. Third, the updated audit and broker-dealer custodial rules may change what evidence finance and operations teams need to produce, which in turn affects system design, key management, and reporting workflows.
A reasonable posture is to treat the proposal as a design specification for a future compliance state, not as a reason to re-platform immediately. The 60-day comment period and the possibility of revision before adoption mean the final rule could differ in detail. However, the core direction — defined custodians, limited self-custody, updated audits — appears consistent across the proposal's stated goals.
Section source: SEC Proposes Rules to Clear Up How Advisers and Funds Can Hold Crypto
For firms that want to move from analysis to implementation readiness, IT Finance supports technical teams in evaluating custody integration, key management, and audit-ready reporting for digital-asset operations. If your team is assessing how the proposed framework would affect your custody architecture, contact IT Finance to discuss the technical and compliance implications.
What to do next
- Map your asset list against proposed custodian coverage. Identify which assets in your current or planned strategies would be covered by qualified custodians, including state-chartered trusts, and which would fall outside that coverage.
- Review your self-custody readiness. If any assets might rely on the self-custody fallback, document the expertise requirements and build a quarterly review process into your compliance calendar.
- Prepare for the comment period. The 60-day window opens once the proposal is published in the Federal Register. If your firm has operational concerns — for example, around audit requirements or the quarterly self-custody review — this is the window to raise them.
- Run a gap analysis on audit and reporting workflows. The updated financial-statement audit and broker-dealer custodial rules may require changes to how you evidence custody and control.
Conclusion
The SEC's custody proposal replaces a long-standing ambiguity with a concrete, if not yet final, framework for holding digital assets. For advisers and fund managers, it creates a basis for planning that did not previously exist. The practical work now is to map your operations against the proposed requirements and engage with the rulemaking process before the comment period closes.
FAQ
Does the proposal allow advisers to hold client crypto themselves?
Yes, but only in limited circumstances. Self-custody is permitted only if the adviser cannot find a qualified custodian ready to take the assets and the adviser has certain required expertise. The arrangement must be reviewed every quarter to determine whether a custodian has become available.
Are state-chartered trusts allowed as custodians under the proposal?
Yes. The proposal would permit the use of state-chartered trusts as custodians for client and fund crypto assets, alongside updates to audit and broker-dealer custodial rules.
When would the rules take effect?
The proposal is not final. A 60-day public comment period will open once it is published in the Federal Register, after which the SEC can revise the rules before any vote to adopt them.
Sources
- SEC maps out crypto custody in new proposal that furthers its digital assets agenda
- SEC Proposes Rules to Clear Up How Advisers and Funds Can Hold Crypto
This article was prepared with the support of AI tools and verified against the public sources listed above.